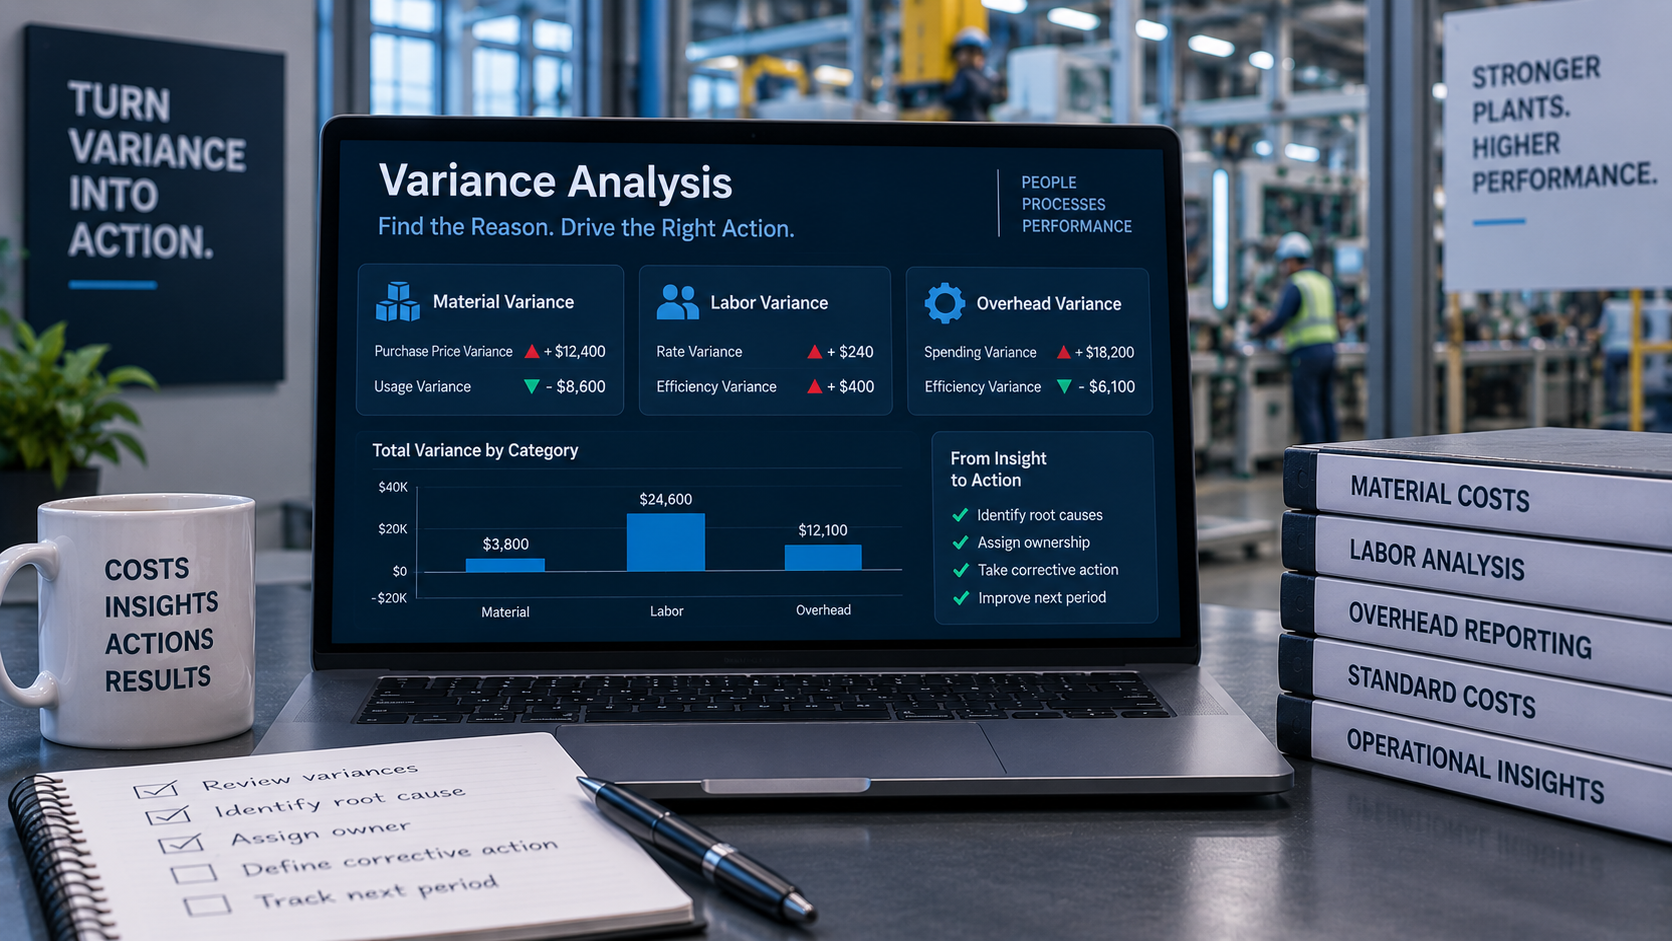
Standard Costing and Real Time Costing Compared for Plants Tracking Manufacturing Overhead


One overview of manufacturing overhead drivers, citing McKinsey research, puts the stake in plain terms: indirect operations in many facilities run 8% to 12% of total operating cost. That is not a rounding error buried in a close package. It is the difference between a product line you think is profitable and one that is quietly funding the rest of the plant, and the costing method you use decides how long that misread lasts. Manufacturing overhead is every production cost that is not direct material or direct labor, which means indirect labor, supervision, maintenance, utilities, depreciation on production equipment, quality inspection, sanitation, consumable supplies, and the facility costs that keep the lines running whether or not you build anything today.
The choice in front of most controllers and plant leaders is not whether to track overhead but when to find out what it actually was. Standard costing assigns overhead at a predetermined rate set before the period starts and reconciles that rate to actual cost after the period closes. Real-time costing records overhead as the transactions land, so applied and actual cost can be compared while the period is still open. Both are defensible, and the better one depends on how much your volume moves, how large your indirect labor pool is, and what your systems can actually capture.
How Each Method Assigns Manufacturing Overhead During the Period
Standard costing commits to a predetermined overhead rate before the period begins. You budget the overhead pool, budget the allocation base, divide one by the other, and then apply that rate to production all period long. OneAdvanced walks the arithmetic through a furniture example in which £11,500 of total indirect costs divided by 5,750 labor hours produces a rate of £2 per labor hour, so a dining table that consumes 10 hours carries £20 of overhead, and a run of 150 tables absorbs £3,000. Every unit that crosses the line gets costed at the rate, regardless of what the utility bill or the maintenance overtime turned out to be.
Real-time costing takes the opposite approach and records indirect costs as they are incurred, posting them to cost centers and pulling them into job and product cost while the period is still open. Nothing is smoothed in advance, so the cost of a Tuesday with three unplanned maintenance calls looks different from the cost of a clean Tuesday.
Under either method, the allocation base is where accuracy is won or lost. A labor-hour base in a facility that has automated most of its direct labor out of the process will systematically distort product cost, because the products that still touch human hands absorb overhead created by equipment they barely use. Choosing machine hours, or activity drivers tied to setups, inspections, and material moves, brings overhead assignment closer to what each product actually consumes. The other recurring failure is definitional rather than mathematical, and OneAdvanced flags it directly: "Ensure raw materials and direct assembly labour are kept strictly out of your overhead calculations." A pool contaminated with traceable costs produces a rate that is wrong for every unit it touches.
When Each Method Surfaces an Absorption or Spend Variance
With standard costing, the sequence is fixed. Production runs, the predetermined rate applies overhead to units, actual overhead accumulates in a separate account, and only when the period closes do you compare the two and calculate the over- or under-applied balance. In practice that number reaches the people who could act on it days or weeks after the last shift of the month has already gone home.
Real-time tracking surfaces the same gap continuously. As indirect costs post, applied and actual overhead can be compared against plan at any point in the month, and the variance can be separated into a spend component, meaning you paid more than budgeted for the overhead you consumed, and an absorption component, meaning volume came in above or below the level the rate assumed. Naming which one moved matters, because they call for different responses from different people.
The consequence of late visibility is the compressed action window. Once the period is closed, the levers that drive indirect cost have already been pulled: the weekend shift was staffed, the contract labor was called in, the maintenance overtime was approved, and the sanitation crew worked the hours it worked. You cannot unspend it. A controller who sees an unfavorable spend variance on the eighth working day still has three weeks to trim discretionary indirect spending, resequence work so it falls inside straight-time coverage, or shift indirect headcount toward the areas actually consuming the hours. A controller who sees the same variance in the close package can only explain it. Both outcomes appear in the ledger; only one of them changes the number.
Disposing of the Over- or Under-Applied Balance
Whatever the method, the period-end balance has to go somewhere, and the accounting treatment depends on materiality. When the over- or under-applied amount is immaterial, it is closed entirely to cost of goods sold, which is the simple and common answer. When the balance is material, it should be prorated across work in process, finished goods, and cost of goods sold in proportion to the applied overhead sitting in each, because the units still on the floor and in the warehouse carry their share of the misapplication just as much as the units already shipped.
The version of this that hurts is a budgeted rate set too low and left alone. Each month applies less overhead than the plant actually consumes, each month's under-applied balance looks small enough to write off to cost of goods sold, and the error accumulates quietly until someone recalibrates or the year ends. The cumulative write-off then lands in a single period, distorting full-period profitability and, worse, leaving every unit margin calculated in the interim understated on the cost side. If those margins informed pricing or product mix decisions, the distortion left the accounting system and entered the business.
Real-time matching reduces the magnitude of the problem because applied cost tracks actual cost as it occurs rather than trailing a forecast. It does not eliminate the period-end true-up. Fixed overhead pools such as depreciation, plant leadership salaries, insurance, and facility costs are incurred on a calendar, not per unit, so they still have to be spread across whatever volume the period produced. Any month whose output differs from the assumed volume will leave a residual balance to dispose of, and the discipline of testing that balance for materiality before dumping it into cost of goods sold applies to real-time systems exactly as it does to standard ones.
Fixed Versus Variable Overhead Behavior as Volume Changes
A single blended overhead rate hides the most useful distinction in the pool. When volume runs above budget, a blended rate over-absorbs fixed overhead automatically, because the plant applies fixed cost to more units than the rate assumed and the favorable variance appears regardless of whether anyone controlled spending. A strong volume month can therefore report a favorable overhead variance while indirect spending is deteriorating, and a slow month can report an unfavorable one while every supervisor on the floor held their budget.
Separating the pools fixes the diagnosis. A fixed overhead pool with its own volume variance and a variable pool with its own spending variance tell you whether the number moved because you built more, or because you paid more per hour of indirect effort. Only the second is a management problem in the short run, and only the first should influence how you talk about capacity.
The behavior also changes decisions upstream of accounting. Fixed overhead per unit declines as volume rises, which means break-even moves with the production plan rather than sitting still in a model. A decision to consolidate a slow-moving product onto fewer, longer runs lowers fixed overhead per unit on those runs and raises it on everything the freed capacity no longer supports. Plants that run a blended rate rarely see that trade clearly, because the rate averages it away before anyone can look at it.
Indirect Labor as the Most Consequential Classification Decision
Direct labor is traceable to a specific unit or job. Indirect labor is not, which is why material handlers, setup technicians, quality inspectors, sanitation crews, maintenance, and line supervision belong in the overhead pool rather than in direct cost. The line between the two is a judgment call in most plants, and it is made at the cost-center level by people who are not thinking about product margin when they make it.
Get it wrong in the direction of overhead and the pool inflates. Hours that should have been traced to a specific job instead spread across everything the plant built, which understates cost on the products that consumed those hours and overstates it on the products that did not. Returning to the OneAdvanced arithmetic makes the mechanism obvious: the rate is the pool divided by the base, so a pool carrying misclassified assembly hours raises the £2 per hour applied to every product, not just the one where the error originated. The same source is blunt about keeping direct assembly labour out of the calculation for exactly this reason.
Standard costing is structurally poor at catching this. The predetermined rate absorbs whatever the pool contains without asking how it got there, so a misclassification made once in a chart of accounts propagates silently across every period until someone audits pool composition, which rarely happens on a monthly cadence. Real-time transaction visibility makes the audit tractable, because indirect labor charges arrive tagged to cost centers, shifts, and work areas while the context is still fresh enough for a supervisor to confirm what those hours actually supported.
Where Standard Costing Still Wins
Standard costing remains the right default in a plant with stable volume and actual overhead that lands close to budget. When the period-end variance is consistently small, delayed visibility costs almost nothing operationally, and the method buys real advantages: predictable unit costs for quoting, a stable basis for performance conversations, and far less transactional bookkeeping than continuous capture requires.
It also produces a clean inventory valuation trail. Standard costs applied through a documented rate, reconciled to actual at period end, and disposed of by a consistent materiality policy give auditors a straightforward path from the general ledger to the balance sheet under GAAP and IFRS. Real-time systems can meet the same standard, but they need additional controls to do it, including governance over how transactions are classified as they post and evidence that the applied amounts reconcile.
The caveat is the one worth repeating to anyone who defends standard costing on audit-trail grounds alone: a clean trail to a bad number is still a bad number. A predetermined rate built on an unrealistic volume assumption or a stale overhead budget will distort product cost for the entire year, and the tidiness of the documentation does nothing to correct it. Recalibrating the rate when the plant's cost structure or volume base shifts matters more than the elegance of the reconciliation.
Where Real-Time Overhead Tracking Changes the Controller's Options
The case for real-time tracking is not better accounting; it is a longer action window. A spend variance visible on the twelfth of the month can still be answered inside the month by trimming discretionary indirect spending, resequencing work, or shifting coverage so indirect hours land where output actually needs them. The larger the indirect share of total cost, the bigger those signals get, which is why the 8% to 12% range cited from McKinsey research matters when deciding how much continuous capture is worth building.
The mechanism that makes the signal actionable is data proximity. When production actuals and cost center detail live in the same system, overhead pool composition reflects live labor decisions rather than a month-old assumption, and a staffing change made Thursday shows up in the cost picture rather than surfacing in a variance six weeks later. Jetson connects operational performance to financial outcomes, continuously reconciling indirect labor, production, and cost from the systems a plant already runs and attributing overhead to the cost centers, shifts, and work areas that actually consumed it. Because applied and actual overhead are reconciled against plan during the period, a spend or absorption variance is visible and explained in dollars while there is still time to trim discretionary indirect spend, resequence work, or move coverage, rather than surfacing six weeks later at close. Jetson reads from the HRIS, time clocks, ERP, and MES you already run rather than standing in for them, so the transaction record your finance team already relies on stays the record. Jetson's implementation team gets customers live in about four weeks rather than months.
Verdicts by Plant Situation
The honest answer to which method to run is that plant situation decides it, and the relevant variables are volume stability, the size of the indirect labor pool, and what your systems can capture at the transaction level.
- Stable volume with actual overhead close to budget: keep standard costing. Lower complexity, lower risk, and a variance small enough that seeing it late costs you nothing you could have recovered.
- Frequent volume swings and a large indirect labor pool: move toward real-time tracking, because mid-period spend and absorption variances are both large and still answerable while the month is open.
- Job-order costing across jobs of varied complexity: real-time capture earns its keep, since a blended standard rate cannot distinguish a setup-heavy short run from a long clean one.
- Process costing with homogeneous output: standard costing holds up well, because the units genuinely do consume overhead at similar rates and the rate is not hiding much.
Mid-size plants with moderate volume variability sit in the ambiguous middle, and there the answer depends less on costing theory than on whether your ERP or MES can capture indirect cost at the transaction level without manual intervention. If it cannot, a well-maintained standard rate with disciplined quarterly recalibration and a real materiality policy on the over- or under-applied balance will serve you better than a real-time ambition that runs on manual entry. If it can, the constraint is usually the labor side of the pool rather than the accounting side, since indirect hours are the piece that moves most and gets audited least. Plants working that problem can request a demo to see how continuously reconciling indirect labor and cost changes how quickly a spend or absorption variance gets explained, while there is still time in the period to act.