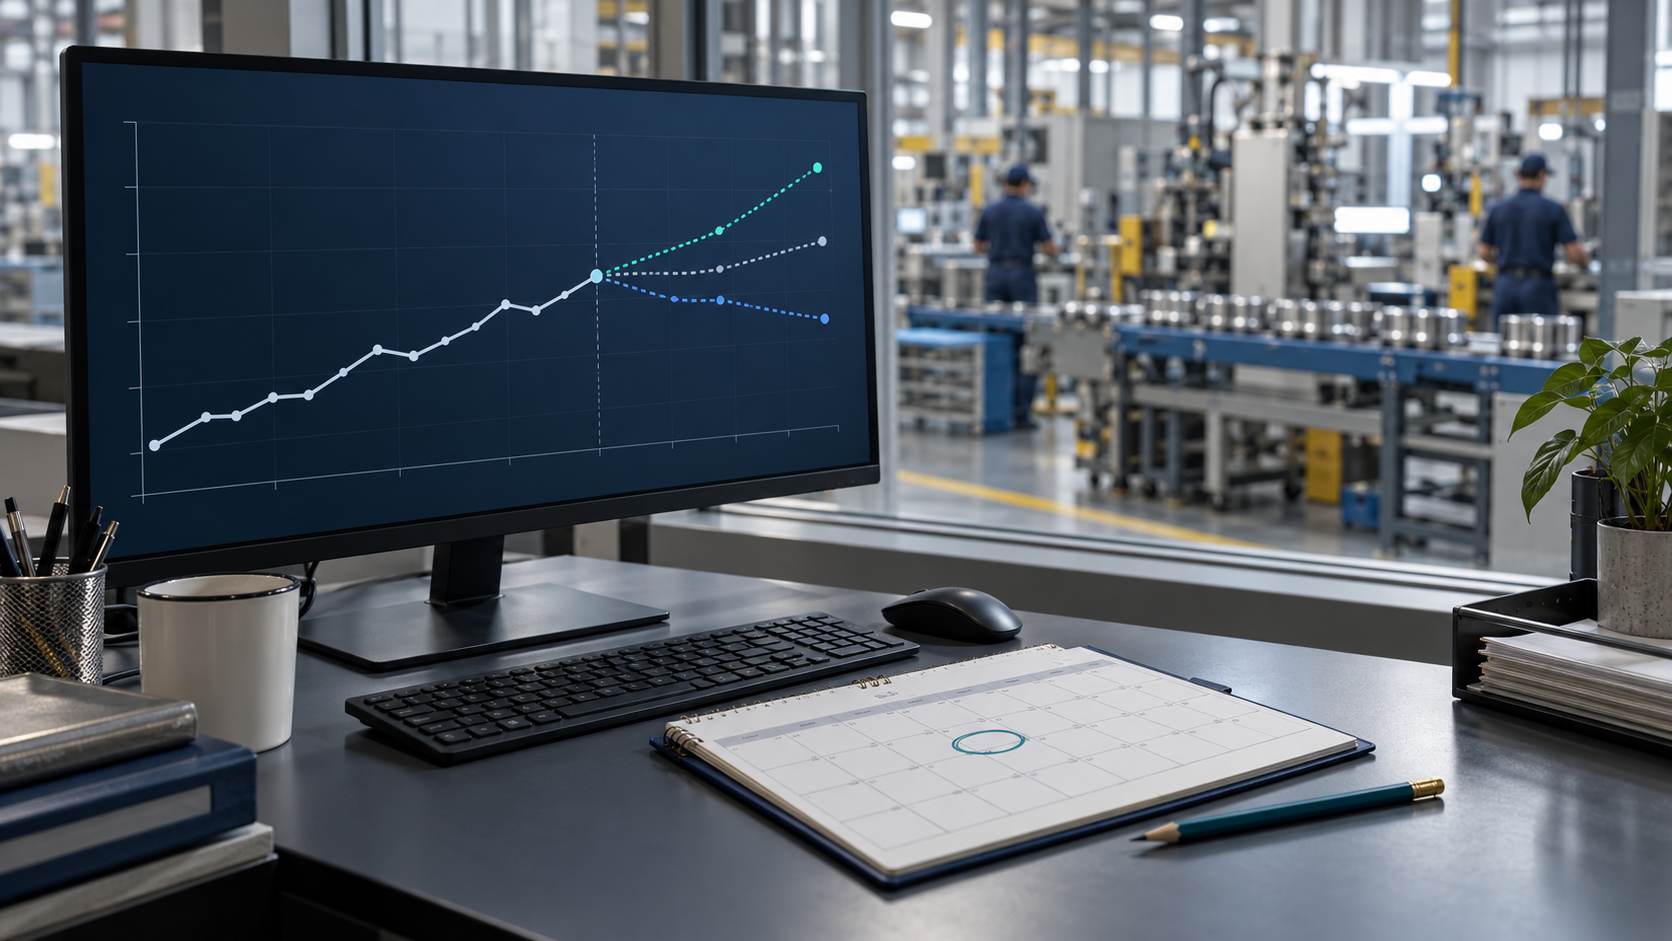
What Operations Finance Actually Is: The Controller's Job of Turning the Floor Into the P&L

Search for "operations finance" and you'll get pages about financial controller career paths: job duties, salary bands, the difference between a controller and a CFO. None of it defines operations finance as its own function. That gap exists because operations finance isn't a job title search engines can index cleanly. It's a slice of work that happens inside controllership, and it's the part of the job that determines whether a plant or warehouse actually understands its own P&L.
Here's the direct definition. Operations finance is the work of connecting what happens on the floor, labor hours, production output, overtime, scrap, to what shows up in the financial statements. It answers a specific set of questions about site performance, in a specific order, and most Finance and Operations teams are only getting through the first two of them.
What Operations Finance Actually Does
Operations finance takes the raw activity of a plant or warehouse: labor hours worked, units produced, overtime paid, materials consumed. It turns that activity into an explanation of site economics. It is not a separate corporate title sitting alongside controller or CFO on an org chart. It's a function performed inside controllership, and at most manufacturing and distribution sites, the person doing it carries the title plant controller.
That's the mismatch behind the search results. Generic controller content describes company-wide accounting oversight, compliance, and close. Operations finance is narrower and more operational: it's the ongoing work of tying labor cost, production cost, and overhead back to what the site actually planned to spend and produce. The plant floor generates that activity every shift, whether or not anyone is watching it in dollar terms. Operations finance is the discipline that makes sure someone is.
The Five Questions Operations Finance Answers
Strip away the accounting vocabulary and operations finance comes down to five questions, asked in this order, for every meaningful cost driver at a site.
Plan: what did we expect labor and production cost to be? This comes out of budgeting and forecasting: standard labor hours per unit, expected run rates, and planned crewing levels against the production schedule. Solid production planning and scheduling makes that expectation explicit before the shift even starts, which is what gives operations finance something concrete to measure actual performance against.
Actual: what did the floor actually do? Actual hours worked, actual units produced, actual overtime paid, actual scrap and downtime. This is where labor, production, and cost data from the shift meet the numbers finance is tracking.
Variance: what's the gap between plan and actual, and in which direction? A crew running under labor standard while still logging overtime is a variance. So is a production line that hit its unit target but burned more labor hours doing it than the schedule called for.
Financial impact: what does that gap cost, in dollars? A labor variance of a few hours a shift sounds minor until it's converted into a weekly or monthly overtime line and compared against site margin.
What next: given the size and cause of the variance, what corrective action makes sense, adjusting the schedule, retraining a crew, renegotiating a staffing agency rate, or accepting the variance because the plan itself was wrong?
That fifth question is where generic variance analysis usually stops short. Reporting a gap between budget and actual is table stakes. Explaining it means tracing whether the gap came from timing, a volume shift, or an actual performance problem on the floor, not just flagging that budget and actual don't match. Operations finance is that explaining work, applied to the plant floor instead of the general ledger.
Why Operations Finance Is Not the Same as Controllership or FP&A
A financial controller's core mandate is company-wide: accounting accuracy, close discipline, internal reporting, and compliance across every entity and location the business runs. Operations finance is a subset of that mandate, focused specifically on site-level production and labor cost rather than the full scope of corporate accounting. A controller who never sets foot in a plant is still doing controllership. Operations finance only exists where floor activity and financial reporting intersect.
FP&A (financial planning and analysis) sits on the other side of the same problem. FP&A teams are supposed to spend their time on forward-looking analysis such as forecasting, scenario planning, and margin modeling, but survey data from FP&A Trends shows FP&A spends about 50% of its time handling data rather than analyzing it. That data-handling burden exists because the underlying numbers for labor, production, and cost actuals often aren't reconciled by the time FP&A needs them. FP&A depends on controllership, and by extension on operations finance, to hand off clean, explained numbers. When that handoff doesn't happen, FP&A inherits the reconciliation work instead of doing the analysis it was built for.
Operations finance sits closer to controllership than to FP&A for that reason. It's not about modeling the next quarter. It's about making sure this week's actuals are accurate and explained before anyone tries to forecast off them.
The Explaining Problem
Even well-run finance teams close the books on a lag. One industry analysis of the controller role found that best-in-class teams close within 5 days, and that's the fast end. By the time a labor or production variance shows up in a finance report, the shift or week that caused it is already gone. Nobody on the floor remembers exactly why overtime spiked on a Tuesday three weeks ago.
That's the real issue, and it's not a reporting problem. Reporting tells you a variance happened: labor cost ran two percent over plan last month. Explaining tells you why: a crew ran below standard for three shifts because of a staffing agency gap, and overtime covered the shortfall. You don't have a reporting problem, you have an explaining problem, and the two require different fixes.
The delay usually comes down to systems, not effort. Labor data lives in the time clock and HRIS. Production data lives in the MES or on the floor. Cost data lives in the ERP. None of them talk to each other automatically, so operations finance spends the days between shift end and month-end close manually reconciling three data sets instead of explaining what they show. Real-time explanation, catching the variance while the shift is still fresh, moves that work upstream, before the number ever hits the P&L instead of after. That's the idea behind real-time production monitoring paired with manufacturing analytics built to connect plant-floor data to financial outcomes: the variance gets explained the same day it happens instead of three weeks later at close.
Where Plant Controllers Fit in Operations Finance
Controller titles scale with how much of the organization they cover. Assistant controllers typically support a single function or process. Divisional controllers oversee a business unit or region. Corporate controllers hold company-wide accounting and reporting. A plant controller sits at the narrowest end of that scope: one site, its production, and its labor cost. This is the one place where the plant controller title fits the operations finance definition directly, because the role is built entirely around explaining a single site's floor-to-P&L gap.
Two examples show what that explaining work looks like in practice, without naming any one site or company. A crew runs consistently under its labor standard for a shift or a week, but overtime still gets paid because the schedule didn't flex to match the shortfall. Nobody disputes the hours; the question is why the standard slipped and whether the overtime was avoidable. Separately, staffing agency invoices show billed hours that don't line up with actual time clock punches at the site. Neither example is a case of Finance catching Operations doing something wrong. Both are ordinary gaps that a plant controller has to reconcile and explain before they quietly erode site margin. Manufacturing analytics that ties floor data to cost data is what makes both gaps visible before month-end instead of after.
What This Means for the Next Variance You See
Next time a labor or production variance crosses your desk, check which of the five questions it actually answers. Most reports handle plan and actual well. Fewer explain the variance's operational cause, translate it into dollar impact, or recommend a next action. Check whether your labor, production, and cost data live in separate systems that someone has to reconcile by hand, and whether that variance gets explained the same day or only at month-end close. If it's the latter, the operational cause is usually too old to act on by the time anyone sees it. Operational reporting with drilldowns can help here, letting you trace a labor or overtime variance back to its cause instead of stopping at the dollar total. And if the same gap keeps showing up shift after shift, that pattern is usually the starting point for a manufacturing cost reduction plan rather than a one-off write-off.
This is the gap AI-native controllership is built to close: platforms that connect to the ERP, HRIS, and time clock systems a plant already runs, reconcile labor, production, and cost data automatically, and surface the financial impact of a variance while the shift that caused it is still recent enough to fix.